World Tax Journal · 28 July 2026
Governing AI in tax administration: four minimum conditions
Published in the World Tax Journal (IBFD): a comparative constitutional framework for the use of algorithmic and AI-assisted systems by tax authorities.
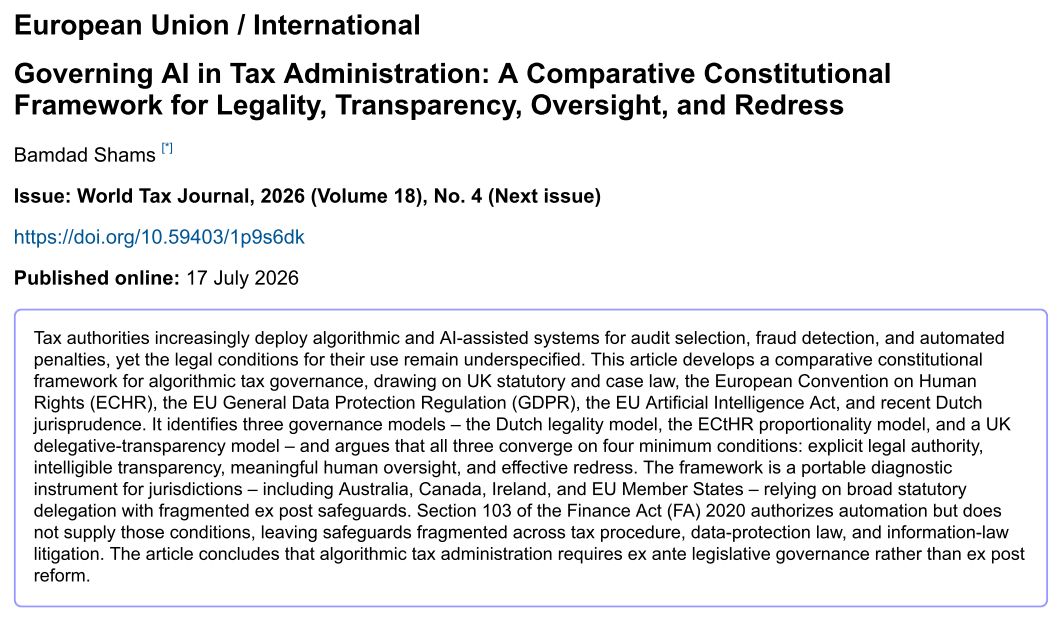
My article “Governing AI in Tax Administration: A Comparative Constitutional Framework for Legality, Transparency, Oversight, and Redress” has been published in the World Tax Journal (Vol. 18, No. 4, 2026), IBFD.
The approach
The article develops a comparative constitutional framework for the use of algorithmic and AI-assisted systems in tax administration. It draws on UK law, Dutch case law, the European Convention on Human Rights, the GDPR and the EU AI Act.
Four minimum conditions
- Explicit legal authority for the use of the system;
- Intelligible transparency towards the taxpayer;
- Meaningful human oversight of the decision;
- Effective redress when the system errs.
In practice
These four conditions provide a checklist that taxpayers and their advisers can use when a tax decision appears to rest on an automated analysis.
My thanks to the editors, reviewers and production team at IBFD.
World Tax Journal, Vol. 18, No. 4 (2026), IBFD.