Virginia Tax Review · 18 November 2026
The Algorithmic Levy: constitutional limits on AI-driven tax administration
Published in the Virginia Tax Review: when tax authorities use machine learning to select audits and automate assessments, which constitutional limits apply in the United States and the European Union?
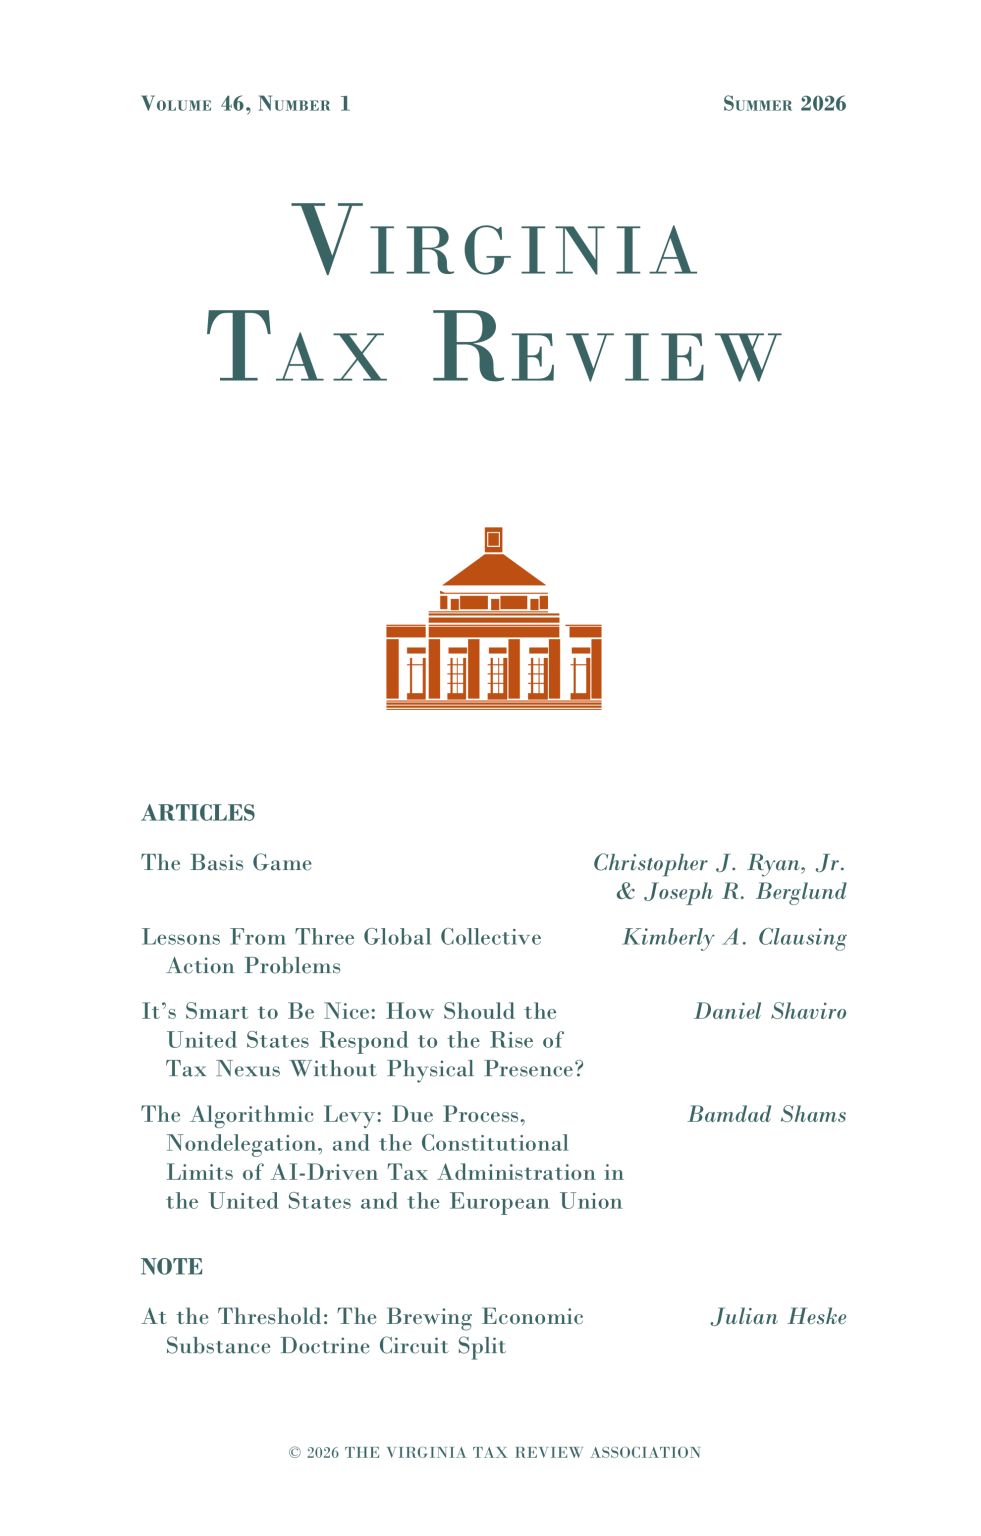
My article “The Algorithmic Levy: Due Process, Nondelegation, and the Constitutional Limits of AI-Driven Tax Administration in the United States and the European Union” has been published in the Virginia Tax Review (Vol. 46, No. 1).
The question
Tax authorities increasingly rely on machine-learning systems to decide which taxpayers to audit and, in some cases, to automate assessments. The article examines the constitutional limits that apply when the state delegates part of its taxing function to such systems.
What the article does
- It analyses the due process and nondelegation constraints on AI-driven audit selection and automated assessment.
- It compares the US constitutional framework with the EU framework.
- It proposes safeguards for both systems.
Why it matters for taxpayers
For companies and their executives, these questions are practical: they shape what a taxpayer can ask to know about the selection of an audit, and how an automated assessment can be challenged.
I am grateful to Ronald Petersen, Olivia Haddox and the editors of the Virginia Tax Review for their careful editing.
Reference: 46 Va. Tax Rev. 121 (2026).